If you are currently in your mid-50s, an important change to the minimum pension age could affect when you can access your retirement savings. For some people, particularly those born between 6 April 1971 and 5 April 1973, careful planning may be worthwhile.
The age at which most people can normally start accessing their private pension savings is changing.
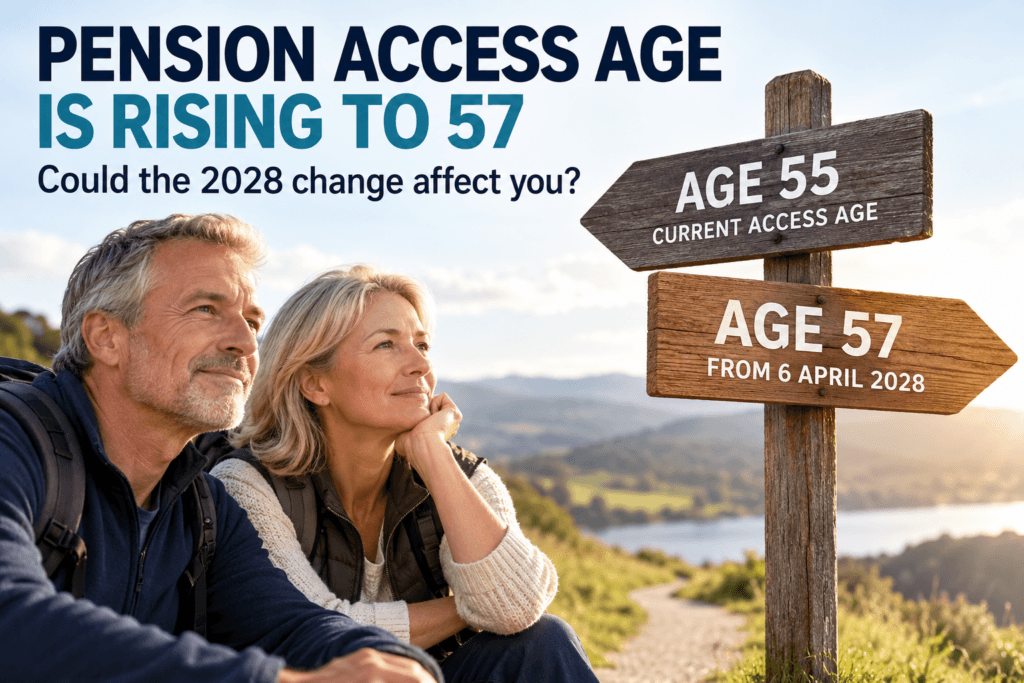
At present, the Normal Minimum Pension Age (NMPA) is 55. From 6 April 2028, it will increase to 57 for most pension savers.
Although that sounds like a straightforward two-year increase, the position is more complicated for some people who will already have reached age 55 when the new rules take effect.
What is the Normal Minimum Pension Age?
The Normal Minimum Pension Age is generally the earliest age at which you can start taking benefits from a registered pension scheme without the payment being treated as an unauthorised pension payment.
It is currently age 55 and will rise to 57 from 6 April 2028.
There are exceptions. For example, some people may have a Protected Pension Age, and separate provisions can apply where benefits are being taken because of ill health.
The rules of the individual pension scheme also need to be considered.
Who will be affected by the pension age increase?
Your date of birth is particularly important.
Born before 6 April 1971?
You should generally be unaffected by the change because you will already have reached age 57 by 6 April 2028.
Born on or after 6 April 1973?
For most people in this group, the earliest age at which they will normally be able to access their pension will be 57, rather than 55.
However, a Protected Pension Age may apply to some pension arrangements.
Born between 6 April 1971 and 5 April 1973?
This is the group for whom the change can be particularly important.
You will have reached age 55 before 6 April 2028, meaning you can potentially access pension benefits under the existing minimum pension age rules.
However, you will not yet have reached age 57 when the new minimum pension age takes effect.
This creates a potentially important transitional period.
The unusual 55-to-57 pension window
Consider somebody who turns 55 shortly before April 2028.
Under the current rules, they may be entitled to start accessing their pension when they turn 55.
On 6 April 2028, however, the Normal Minimum Pension Age becomes 57.
HMRC is introducing transitional provisions intended to ensure that people who have already become entitled to certain pension benefits before the change can continue receiving those benefits after 6 April 2028.
However, this does not necessarily mean that all of the person’s remaining untouched pension savings can continue to be accessed after the rule changes.
Depending upon the circumstances, they may have to wait until age 57 before accessing further benefits.
This is why people born between 6 April 1971 and 5 April 1973 should be particularly aware of the change.
Does this mean I should take my pension before April 2028?
No.
The change in the minimum pension age should not, by itself, be a reason to start taking pension benefits.
Accessing a pension is an important financial decision and can have tax and retirement-planning consequences.
For example, taking benefits could affect:
- how long your retirement savings may last;
- the amount remaining invested for future growth;
- your income tax position;
- the tax-free cash available from your pension;
- your future retirement income strategy; and
- in some circumstances, the amount that can subsequently be contributed to money purchase pensions with tax relief.
The important point is therefore not that people should rush to access their pensions before April 2028, but that those potentially affected should understand their position and plan ahead.
Could you have a Protected Pension Age of 55?
This is another important consideration.
Some pension schemes have a Protected Pension Age, which can allow qualifying members to continue accessing benefits earlier than the new Normal Minimum Pension Age.
Importantly, a Protected Pension Age generally relates to the particular pension scheme or benefits, rather than automatically applying to every pension you hold.
It is therefore possible for somebody with several pensions to have different minimum access ages applying to different arrangements.
Whether protection applies depends on the rules and history of the pension arrangement.
Be particularly careful before transferring a pension
If you are considering transferring or consolidating pensions, the minimum pension age is another feature that should be checked before proceeding.
A pension may have valuable age-55 protection and the way in which that protection operates following a transfer can depend upon the circumstances.
For this reason, pension consolidation should not simply be viewed as an administrative exercise.
Before transferring, it is sensible to establish whether your existing pension has a Protected Pension Age and whether that protection would continue following the proposed transfer.
What should you do if you are aged between 55 and 57?
If the 2028 change could affect you, a useful starting point is to review your pensions and retirement plans.
Consider questions such as:
When do you actually expect to retire?
If you have no intention of accessing your pensions before age 57, the change may make little practical difference to you.
Do any of your pensions have a Protected Pension Age?
Your pension provider or adviser should be able to help establish this.
Were you planning to use pension money between ages 55 and 57?
For example, pension tax-free cash or income may form part of a plan to repay borrowing, reduce working hours or bridge the period before other retirement income begins.
Do you have several pensions?
Different arrangements may have different rights and protections, so they should be considered individually.
Are you considering consolidating or transferring pensions?
Check the minimum pension age position before making an irreversible decision.
Retirement planning is about more than reaching a particular age
Being allowed to access a pension does not necessarily mean that doing so is the right financial decision.
A sustainable retirement strategy should consider your wider circumstances, including other savings and investments, expected expenditure, State Pension entitlement, taxation, investment risk and the income you may require throughout retirement.
For some people, leaving pension savings invested for longer may be appropriate. For others, accessing part of their pension earlier may form part of a carefully structured retirement plan.
The important thing is to make the decision for the right financial reasons, rather than simply because a particular birthday has been reached.
Planning to retire around 2028?
The increase in the Normal Minimum Pension Age is still some way off, but retirement planning often benefits from starting well in advance.
This is particularly relevant if you were born between 6 April 1971 and 5 April 1973, or if you have been planning on accessing pension savings from age 55.
Understanding which pensions you have, when they can be accessed and how they fit into your wider retirement plans can help avoid unexpected surprises.
At LFP Asset Management, we can help you review your existing pension arrangements and consider how they fit into your retirement plans.
If you are approaching retirement and would like to discuss your options, please contact us to arrange an initial conversation.
Frequently Asked Questions
The Normal Minimum Pension Age is scheduled to increase from 55 to 57 on 6 April 2028.
Potentially, yes. Under the current rules, most people can normally access pension benefits from age 55. However, if you will still be under 57 on 6 April 2028, the transitional rules need to be considered carefully.
Transitional provisions are intended to allow qualifying benefits to continue after the Normal Minimum Pension Age changes. However, this does not necessarily mean that previously untouched pension benefits can also be accessed before age 57.
A Protected Pension Age is a right under qualifying pension arrangements that can allow benefits to be taken before the prevailing Normal Minimum Pension Age. Protection is generally scheme-specific, so it should be checked for each pension you hold.
Not simply because the rules are changing. Taking pension benefits can have significant tax, investment and retirement-income consequences. The decision should be based on your individual financial circumstances and objectives.
Important Information
This article is for general information only and does not constitute personal financial or investment advice. Pension and tax rules can change and their effect depends upon individual circumstances and the rules of the particular pension scheme. Transitional provisions relating to the increase in the Normal Minimum Pension Age are still being finalised and may be subject to change.
The value of investments can fall as well as rise and you may get back less than you invest. Before making decisions about accessing or transferring pension benefits, you should consider obtaining appropriate financial advice.